



Find the right starting point
A damaged property can create several different problems at once. The insurer may dispute coverage, the association may disagree about repair responsibility, and a contractor may have performed work you question. Start by identifying who you believe has an obligation and what decision or action you are challenging. An insurance claim and a dispute with a board are not the same legal matter.
| What you are dealing with | Where to start |
|---|---|
| Your own property insurer denied, delayed or underpaid a claim | Start with Florida property insurance representation and the specific damage service below. |
| An HOA is imposing a disputed fine, enforcing rules inconsistently or withholding records | See representation for Florida homeowners in HOA disputes. |
| A condominium association is not addressing repairs, records or another owner concern | See condominium owner representation. |
| You were injured and another party may be responsible | See Florida personal injury claims or our Clearwater injury service. |
You do not need to select the perfect legal label before contacting us. Explain what happened, the person or company involved, and any deadline or document requiring your response. We can discuss whether the matter fits the firm’s services and what information is needed next.
Property insurance disputes by type of damage
- Water damage: plumbing failures, leaks and disputes about sudden discharge, seepage or excluded flood.
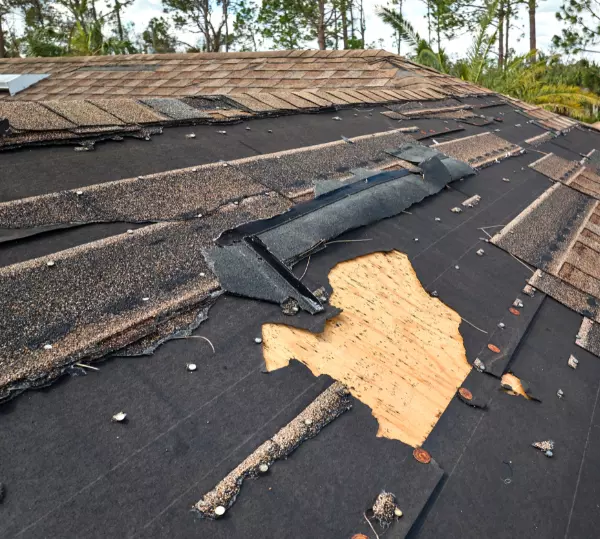
- Roof damage: supported storm repairs, replacement disputes, matching and interior damage connected to a roof loss.
- Fire and smoke: building repairs, smoke cleaning, belongings, temporary housing and cause investigations.
- Hail damage: impact evidence, functional damage and disagreements about the repair scope.
- Hurricane damage: wind, rain intrusion, flood distinctions and disputed insurance payments.
- Mold insurance claims: moisture-related property losses, remediation evidence and fungi limitations. The firm’s mold insurance service does not handle landlord mold cases.
- Insurance bad faith: evaluation of claim handling and whether the requirements for an additional legal remedy can be met.
The cause of damage and the type of insurance both matter. A homeowners policy, condominium unit policy, rental policy and commercial policy may protect different interests. Standard homeowners coverage generally excludes flood, which may require a separate policy. A list of services is not a statement that every loss is covered.
Hurricane representation and claim-file guides
For a broad explanation of coverage, deductibles and representation, visit our Florida hurricane damage attorney page. For a practical timeline, inventory and estimate checklist, use the hurricane insurance claims guide.
An existing named-storm dispute needs attention to the original reporting date, prior payments and any release or proceeding. Use the pages for Ian, Idalia, Debby and Helene for those questions. The Idalia file guide also explains how to organize an older claim. A storm-specific page does not mean a new claim is necessarily still timely.
Association disputes and insurance can overlap
Homeowners and condominium owners may face disputed assessments, maintenance failures, records issues, architectural decisions or enforcement concerns. The governing documents, applicable statute and actual board decision are central. Condominium and HOA law have different provisions, so those matters should not be treated as interchangeable.
If water enters a unit because a common component was not maintained, there may be questions about repair responsibility, association conduct and more than one insurance policy. Identify each issue and bring the declaration, correspondence, photographs and relevant policy records. An insurer’s payment does not necessarily resolve the association dispute, and a board’s responsibility does not automatically establish insurance coverage.
Personal injury requires a different evidence file
An injury claim focuses on responsibility, causation, medical evidence and the effect on the injured person. It may involve a vehicle accident, fall, defective product, medical-treatment concern or other event requiring a specific assessment. Appropriate medical care, incident evidence, witness information and insurance communications are useful starting points.
Injury deadlines and comparative-fault rules require current, case-specific review. Do not assume every claim has the same deadline or that partial fault always permits recovery. Our Florida personal injury page explains damages, fees, insurance and the claim process in more detail.
What to prepare before contacting the firm
- A short account of what happened and the dates that matter.
- The insurer, association, person or business involved and any claim or reference number.
- The decision, demand, denial, fine, estimate or proposed settlement you want reviewed.
- The relevant policy, governing documents or other agreement if available.
- Photographs, communications and records that explain the issue.
- Any existing lawyer, public-adjuster or contractor agreement and any pending deadline.
Missing a document does not prevent a first conversation. Identify urgent dates immediately, and ask how to send sensitive information securely instead of placing confidential identification or financial details in a general contact form. Contacting the firm alone does not establish representation; acceptance and written terms need to be addressed.
A free evaluation and a clear discussion of next steps
Krapf Legal is based in Clearwater. Learn about the firm and team, then request a free case evaluation or call 727-777-7450. The conversation can help identify the issue, missing information and whether representation is available.
If representation is proposed, review the fee arrangement and case expenses in writing. Different services may use different terms. Ask who will handle the matter, how updates will be provided and what the next concrete step would be. Neither a free consultation nor another client’s result guarantees a particular outcome.
Our Clearwater office is at 2790 Sunset Point Road, Clearwater, FL 33759. Call 727-777-7450; published office hours are Monday–Friday, 8:00 a.m.–5:00 p.m. See the contact page for directions and consultation arrangements.
Questions and answers
Which Krapf Legal service should I choose?
Start with the problem: your insurer’s decision, an HOA or condominium association issue, or an injury caused by another party. If more than one applies, explain each during the initial conversation.
Does the firm help Florida property owners outside Clearwater?
Krapf Legal is based in Clearwater and represents Florida property owners. Provide the property location and issue so the team can assess the particular matter and consultation arrangements.
Do you represent homeowners against their HOA?
The HOA service page addresses owner concerns such as enforcement, records, assessments, architecture and maintenance. The governing documents and facts determine the available options.
Is a condominium dispute the same as an HOA dispute?
No. Different statutes and governing documents apply. Identify whether the property is a condominium or an HOA community and provide the relevant declaration and board correspondence.
Can an insurance dispute also involve the association?
Yes. Repair responsibility, association conduct and insurance coverage can be separate questions arising from the same damage. More than one policy or potential claim may need review.
Does your mold insurance service handle landlord mold cases?
No. The firm’s stated mold insurance service concerns property insurance disputes and excludes landlord mold cases. Explain the property interest and policy involved when contacting the team.
Does a denial automatically create a bad-faith claim?
No. A claim for policy benefits and a separate bad-faith remedy have different requirements. The facts, claim handling and applicable law need review.
Can I get help with an older hurricane claim?
An existing dispute can be reviewed, but original notice, policy duties, prior agreements and deadlines determine what remains available. A new claim, supplement and unresolved timely reported claim are different situations.
Do I need every document before scheduling a consultation?
No. Start with the key decision, dates and records available. Identify missing information and any urgent deadline so the first discussion can be focused.
How much is the first evaluation?
Krapf Legal offers a free case evaluation. Any proposed representation should explain attorney fees, case expenses and responsibilities in a written agreement.
Will I need to file a lawsuit?
Not every matter requires litigation. The appropriate route may involve evidence gathering, negotiation or an applicable dispute process. The options depend on the service, documents and facts.
Can you promise a recovery or completion date?
No. Coverage, evidence, legal requirements and the course of the dispute affect the result and timing. The team can explain the next step and material uncertainties after reviewing the matter.
How quickly must a property insurer respond?
Current Florida law generally uses a 60-day pay-or-deny framework for certain property claims, with exceptions, tolling and applicability requirements. A response deadline differs from a guaranteed settlement date. Bring the claim and communication dates for a specific review.
What is a first-party property insurance dispute?
It is a disagreement over benefits under your own property policy, such as a denial or an incomplete payment. A claim that another person caused the damage is a different liability question. Our property damage service explains the policyholder process.
Do I have to accept the insurer’s settlement offer?
No offer should be accepted without understanding the supported loss, payment calculation and release terms. Ask whether it is an undisputed payment or a final settlement and review any rights being resolved. The property damage service explains those distinctions.
Can I seek more benefits after a claim was closed?
Possibly, but a closure letter, signed release, appraisal award and judgment have different consequences. Review the policy, original reporting, prior agreements and deadlines before assuming a new estimate permits another payment.
What should I tell an attorney about problems with my claim?
Provide a complete, accurate account, including prior damage, earlier statements, missing documents, signed agreements and unfavorable evidence. Do not hide or delete relevant material. That information helps assess the claim and avoid preventable surprises.
How is the amount of a property insurance claim determined?
The supported covered loss is evaluated under the policy’s valuation terms, limits, deductible and prior payments. A repair quote or policy limit alone does not establish the payable amount. Ask for an itemized calculation and supporting scope.
Can I handle a straightforward property claim myself?
Some owners handle small, undisputed claims without counsel. Legal review may be useful when coverage, scope, deadlines, formal statements or a release are disputed. Compare the issue, amount, evidence and costs before deciding.
What should I do after a theft, burglary or vandalism loss?
Protect people, report the incident to the appropriate authorities and insurer, and preserve photographs, an inventory and supporting records. Coverage and proof requirements vary. The property damage service page explains how to organize a policy review.
Can lightning, a power surge or a fallen tree be covered?
Possibly, depending on the policy, cause and damaged property. Preserve professional findings and itemized repair records. A tree-removal expense, equipment failure and liability for a neighbor’s damage may involve different provisions.
What if another person caused the damage?
A liability claim against that person may be distinct from a claim under your own policy. Identify the conduct, property interest and available insurance; do not assume your insurer’s decision resolves the other party’s responsibility.
Is vehicle damage part of a homeowners property claim?
Vehicle damage generally requires review of applicable auto coverage or a liability claim, rather than treating it as damage to the insured building. Explain the property involved so the issue is directed appropriately.
How long do I have to report or sue over property damage?
Reporting duties, supplemental-claim deadlines and lawsuit limitations are different. The policy, loss date, claim history and legal theory matter. The detailed property and named-storm pages explain what dates and documents to bring for a review.
Can an insurer close a claim or refuse renewal after I file?
Claim closure and policy renewal are different decisions with different rules. A release or settlement may also affect rights. Obtain the relevant letter and stated reason for a specific review.
What is insurance appraisal?
Appraisal is a policy procedure generally used to determine the amount of loss, with its own conditions and costs. It does not automatically resolve every coverage dispute. The property damage page explains appraisal, eligible mediation and litigation as distinct options.