Water Damage attorneys / Florida

Florida Water Damage Insurance Claim Lawyers

A dry room is not always a fully repaired room. Water can damage flooring, cabinets, insulation, and hidden building materials long after the initial cleanup. From our Clearwater office, Krapf Legal helps Florida property owners address denied, delayed, or underpaid water damage insurance claims and understand what the policy may actually pay.

Free case evaluationPersonal attention
Prefer a conversation? Call our team.727 777 7450

Free Case Evaluation

We offer a free consultation to discuss your case and how we can help. We care about you and want to support you through this difficult time.

Please do not include confidential documents, financial account details or Social Security numbers. Sending this form does not establish an attorney-client relationship. For urgent help, call 727 777 7450.

01 / You’re in the right place

When the damage is clear, but your claim isn’t.

Start with the source of the water, the policy in force, and the insurer’s explanation. We help connect those facts to the repairs, damaged belongings, and covered expenses that still need to be addressed.

Get a free case evaluation

Situations we can help you navigate

01

Leaks and plumbing failures

02

Damage beyond the visible surface

03

Disputed repair estimates

Every situation is different. Let’s take a closer look at yours.

Explore the complete water damage guide9 more topics · Coverage, disputes, and next steps

Which kinds of water damage may be covered?

Coverage depends on the policy and cause of loss. The cost of repairing a failed component can be treated differently from resulting damage to otherwise undamaged property. A burst pipe, worn pipe, leaking shower, appliance discharge, and surface flood are not interchangeable events.

Water sourceCoverage questionUseful evidence
Burst or leaking plumbingWas there a covered discharge? Do water-damage or seepage limitations apply?Plumber’s report, failed part, repair invoice, first observed damage.
Dishwasher, water heater, or washing machineWhat caused the release, and which resulting damage is covered?Appliance condition, photographs, service records, affected-room inventory.
Roof or window intrusionDid a covered event create damage or an opening, and what does the policy require?Roof inspection, storm history, entry-point photographs, interior moisture records.
Sewer or drain backupIs backup coverage present, and what deductible or limit applies?Endorsements, drain findings, source and contamination reports.
Storm surge or rising surface waterDoes a separate flood policy apply?Flood policy, water-level evidence, timing, separate wind and flood records.

Ordinary homeowners coverage generally excludes flood as defined by the policy. NFIP policy information explains why a flood claim must be evaluated separately. Do not label all hurricane water as flood or assume every indoor leak is insured.

What to do after discovering a leak

  1. Protect people first. Avoid unsafe electrical conditions, contaminated water, or unstable materials. Use qualified emergency help when needed.
  2. Stop ongoing damage when safe. Shut off the source if appropriate and arrange reasonable emergency mitigation. Keep work orders and receipts.
  3. Notify the insurer promptly. Obtain a claim number and keep proof of your notice. Do not delay notice while waiting for every estimate.
  4. Record the condition. Photograph the source, each affected room, materials, and belongings before removal when safe. Include wider views and close-ups.
  5. Preserve evidence and access. Coordinate inspection before destructive work where feasible, while still preventing further damage. Ask about retaining failed parts or samples safely.
  6. Keep the file together. Save estimates, drying logs, invoices, temporary-housing costs, and every insurer letter.

Tell the truth about what you observed and what remains uncertain. “I first noticed the stain Tuesday” is different from guessing when a hidden leak began. A clear chronology is more useful than adopting a contractor’s or adjuster’s unverified conclusion.

Hidden moisture, mold, and the scope of repairs

An estimate based on visible staining may miss wet insulation, subflooring, cabinet components, or moisture behind finishes. A useful inspection identifies the affected materials, their condition, the moisture source, and the work needed to restore covered damage. Drying equipment invoices should connect dates, equipment, affected areas, and any available readings.

Mold can introduce separate testing, containment, remediation, and policy-limit questions. It is not automatically covered simply because water damage occurred. Keep the underlying water-loss investigation connected to the remediation plan and distinguish testing, removal, reconstruction, and belongings. Our mold insurance claim page explains that part of the review.

A lawyer does not replace a licensed plumber, remediation professional, engineer, or health professional. The appropriate specialist depends on what is disputed. We evaluate which evidence would answer the insurer’s stated concern rather than ordering unnecessary reports by default.

Compare the insurance payment with the actual repair scope

Do not compare only the bottom-line dollar amounts. Match the insurer’s estimate against the contractor’s scope room by room and item by item. Look for omitted removal, access, drying, materials, labor, reconstruction, permits, and supported code-related work. Explain why each disputed item is necessary and how it relates to the covered loss.

Separate the gross covered estimate from the amount payable now. Deductibles, limits, exclusions, prior payments, and depreciation can change the check. Replacement-cost coverage may involve conditions for recovering depreciation after repairs; an actual-cash-value policy operates differently. A contractor’s higher quote does not by itself prove that the insurer owes the difference.

For example, a payment covering paint may not address documented wet drywall and insulation. The useful response is an inspection and itemized scope explaining removal, drying, and reconstruction—not simply a demand for a larger settlement. This example illustrates evidence organization, not a promised result.

Denied, underpaid, or delayed: choose the response that fits

  • Denial: request the written explanation and policy provisions relied on. Compare them with the source investigation and facts, including any alleged prior damage or notice problem.
  • Underpayment: identify accepted coverage, omitted work, disputed pricing, and any incorrect deductions. Submit a supported supplement within applicable requirements.
  • Delay: maintain a dated communication log, confirm what information remains outstanding, and review whether applicable response obligations have been met.
  • Disputed cause: develop evidence answering the actual issue, such as sudden discharge versus repeated seepage or water entry versus rising floodwater.

A request for reconsideration, additional inspection, mediation, appraisal where available, or litigation may be appropriate. Appraisal commonly concerns valuation and is not a universal solution to coverage disputes. A denial or delay alone does not automatically establish a separate bad-faith claim.

Deadlines, proof of loss, and insurer requests

Notice to the insurer, a sworn proof of loss, cooperation obligations, supplemental submissions, and a lawsuit have different requirements. The current Florida property-notice statute generally uses one year for an initial or reopened claim and eighteen months for a supplement, measured from the loss, with qualifications. Its application to your policy and loss date must be checked. See section 627.70132.

Those periods do not replace the policy’s prompt-notice and cooperation duties or determine every civil-action deadline. Do not assume a late discovery, reopening request, complaint, or negotiation automatically extends time. Send any proof-of-loss request, examination-under-oath notice, or deadline letter for review immediately and respond accurately through the appropriate process.

Business losses, condo leaks, and other parties

A commercial water claim may involve inventory, tenant improvements, equipment, extra expense, or business-income coverage. The policy’s trigger, waiting period, limits, and records matter. Keep financial losses separate from building and contents estimates, and preserve sales, payroll, occupancy, and interruption records where relevant.

In a condominium, the association’s maintenance obligation, unit-owner coverage, association insurance, and a possible claim against a neighbor or contractor require separate analysis. Preserve the declaration and incident reports. An association’s responsibility for a shared pipe does not automatically decide who insures every interior finish. Our condo owner service addresses that distinction.

If you already hired a restoration company or public adjuster, bring the agreement, invoices, reports, and any assignment or payment authorization. We need to understand who has authority, what has been promised, and what obligations you have already undertaken.

How Krapf Legal reviews your water damage dispute

We begin with the complete policy, claim chronology, insurer decision, photographs, professional findings, and payment history. We explain the disputed coverage or scope, identify missing support, and discuss an appropriate strategy. If retained, the work can include a supported claim presentation, communication and negotiation, evaluation of contractual dispute options, and litigation when warranted.

Ask how the written fee agreement handles attorney fees, expert costs, filing fees, and any recovery. A free initial consultation is separate from the terms of representation. We do not promise a particular recovery or assume an insurer will reimburse all costs.

Krapf Legal serves Florida property owners from Clearwater. Review Grant W. Krapf’s profile and our firm background. Call 727-777-7450 or request a water damage claim review with your claim number, loss date, decision letter, and any upcoming deadline.

What clients have shared

  1. “Excellent company with superb customer service!” –Paul Grynewicz
  2. “Very professional, knowledgeable, and reliable. I highly recommend Krapf Legal to find appropriate resolutions to your unique legal needs.” -Lisa Fiene
  3. “Grant is a very bright and hardworking attorney who will put in the work to make sure he obtains you the best results possible.” -Rich Cartlidge

These accounts describe individual experiences. Results and timing depend on the facts of each matter.
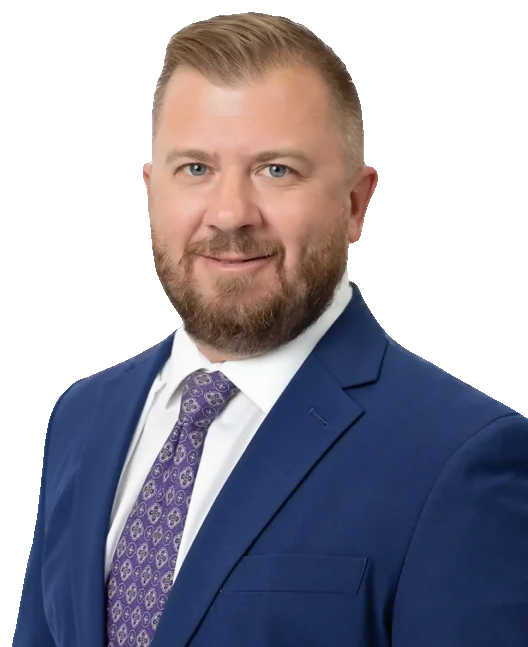
Grant W. Krapf, Managing Attorney and President
Grant W. KrapfManaging Attorney · President

The people behind your case

Someone who listens.
A team that shows up.

At Krapf Legal, your case starts with a conversation. Our Clearwater team takes the time to understand what happened and what moving forward means for you.

Meet your advocates
“Grant & his staff are extremely professional. They really care about their clients,and help in every aspect of your situation. I highly recommend this practice.”
— Diane Schrutt, Krapf Legal clientRead client reviews ↗

A team in your corner

What happens
when you reach out.

You don’t have to have all the answers before you reach out. We’ll start with your story.

  1. 01

    Tell us what happened.

    Start with a free case evaluation. Share your situation, your questions, and where things stand.

  2. 02

    Understand your options.

    Our team reviews the information you provide and discusses how we may be able to help.

  3. 03

    Move forward together.

    If we take your case, we build a strategy with you and keep you informed along the way.

A few things you may be wondering

Good questions.
Clearer answers.

For advice about your specific situation,
start a conversation

01

Is a burst pipe covered by homeowners insurance?

A covered accidental discharge may support payment for resulting damage, but the policy, cause, exclusions, and endorsements control. Replacing the failed pipe itself can be treated differently from repairing wet walls or floors. A plumber’s findings and the complete policy are important starting points.

02

What if the insurer says the leak was gradual?

Request the specific exclusion and factual basis. Preserve the first-discovery timeline, prior condition photographs, repair history, and plumber or other expert findings. Hidden moisture does not automatically prove either a sudden or long-term loss; the evidence must address the actual cause and duration.

03

Does insurance cover a slab leak or cast-iron pipe problem?

There is no automatic answer for every slab or cast-iron system. Resulting water damage, access or tear-out costs, and repair of the pipe may have different treatment. Review the relevant endorsements, plumbing report, and scope before assuming the whole system replacement is insured.

04

Are shower leaks and failed water heaters covered?

They can raise different issues depending on the failed component, discharge, repeated seepage, and policy terms. Preserve the source inspection and resulting-damage record. A maintenance exclusion affecting a component does not by itself answer every question about the damage around it.

05

Does homeowners insurance cover rain coming through my roof?

It depends on how rain entered and what the policy requires. A covered storm-damaged roof can differ from wear, faulty installation, or an existing opening. Document the roof and interior separately and connect the entry point to the claimed event.

06

Is sewer backup the same as ordinary plumbing damage?

No. Sewer or drain backup may be excluded or subject to a separate endorsement, limit, or deductible. The source matters. Obtain a professional explanation of what happened and review the backup language instead of relying on the general phrase “water damage.”

07

Can I start repairs before the adjuster arrives?

Reasonable emergency work may be needed to prevent more damage. Document conditions and costs, notify the insurer, and allow inspection before permanent or destructive work when feasible. Safety comes first. Avoid discarding useful evidence unnecessarily or waiting while avoidable damage continues.

08

What should I say to the water damage adjuster?

Give accurate observations, dates, and documents. Distinguish what you personally know from a professional’s opinion or an estimate. Do not guess about the age of hidden damage or conceal prior problems. Request written explanations of coverage decisions and ask for clarification when a question is unclear.

09

Does insurance pay for mold after a water leak?

Possibly, depending on the covered cause and any fungi endorsement, sublimit, exclusion, and mitigation duties. Document the water event and remediation need together. Mold removal, testing, rebuilding, and damaged belongings can require separate line items and coverage analysis.

10

Will insurance pay for a hotel while repairs are underway?

Loss-of-use or additional-living-expense coverage may apply when a covered loss makes the home unfit to live in, subject to policy conditions and limits. Keep receipts and document additional costs compared with ordinary living expenses. A repair project alone does not guarantee hotel reimbursement.

11

What is the average water damage insurance payout?

An online average does not value your loss. The cause, affected materials, policy limits, deductible, depreciation, and supported repair scope determine the analysis. We review the disputed items and payment calculation instead of treating a national average as an entitlement.

12

Can a lawyer help after my claim was denied?

Yes, a denial can be reviewed for its factual and policy basis, applicable deadlines, and available response. Bring the denial, full policy, photographs, source report, and prior submissions. Review does not guarantee that an excluded or unsupported claim can be recovered.

13

Can I seek more after receiving a payment?

A further payment may be possible if covered damage was omitted and the required procedure and deadlines are satisfied. Check whether the payment came with a release, settlement, or other limitation. Do not assume every check is final or that every closed file can be reopened.

14

Do I need a public adjuster or an attorney?

A public adjuster generally assists with preparing and negotiating an insurance claim within the adjuster’s licensed role. An attorney can advise on legal rights and represent you in litigation. The dispute and existing contracts help determine what assistance is useful and whether overlapping fees need review.

15

Can I choose my own restoration contractor?

Check the policy and any applicable repair-option or managed-repair terms before signing. Contractor selection, insurer payment, and contractual obligations are separate questions. Obtain a written scope, licensing information where required, price, and payment terms, and preserve any agreement already signed.

16

What if my contractor’s estimate is higher than the insurer’s?

Identify the specific scope and pricing differences and the evidence supporting each one. A higher total alone is not enough. Photographs, moisture records, material specifications, measurements, and a reasoned reconstruction scope can help establish whether the insurer omitted covered work.

17

How long does a water damage claim take?

Timing depends on the investigation, documents, scope disputes, repairs, and any formal proceedings. Applicable insurer response requirements also need review with their exceptions. We can discuss the next steps after seeing your file; no general timeline guarantees a settlement or repair date.

18

How much does it cost to hire Krapf Legal?

The initial case evaluation is free. If representation is offered, the written agreement explains the fee arrangement and responsibility for expenses. Ask how any contingency fee is calculated, which costs may be incurred, and what happens if there is no recovery.

19

What if I found the damage after buying the property?

Identify when the damage occurred, the applicable policy, ownership at the time, disclosures, and any earlier claim or repair. A new owner does not automatically acquire every prior insurance claim. The issue may involve coverage, seller disclosure, contractor work, or several separate matters.

20

Can I handle a straightforward claim myself?

Yes. An owner may submit a claim and supporting records without counsel. Legal review becomes more useful when coverage, valuation, deadlines, a release, or insurer conduct is disputed. The decision should reflect the complexity and value of the actual problem.

21

What is a shower-pan leak, and why does the cause matter?

The shower pan is part of the assembly intended to contain and direct shower water. A failure can affect nearby floors or walls. A qualified inspection should identify the source, duration and resulting damage; the cost of fixing a defective component may be treated differently from resulting damage under the policy.

22

Is an inspection included in the free case evaluation?

The initial legal case evaluation is free. Do not assume every inspection, engineering opinion or other professional service is free; ask what work is proposed, who performs it and whether any cost applies before it is arranged.

23

Do I need a lawyer for a small claims insurance dispute?

Some eligible individual claims may be handled without counsel, but court rules, policy proof, deadlines and legal defenses still apply. Entity-representation rules may differ. Consider the amount, complexity, available remedy and costs before choosing a forum; no general win-rate prediction is reliable.

24

Must I speak to a lawyer before notifying my insurer?

No. Do not delay required notice while waiting for an attorney or a complete estimate. Report known facts accurately and keep confirmation. Legal advice can be useful alongside that process when coverage, statements, deadlines or a proposed settlement require review.

Let’s move forward

Tell us what happened.
We’re ready to listen.

You don’t need to have all the answers. Start with a conversation.

Get a Free Case Evaluation 727 777 7450

Monday–Friday 8:00am–5:00pm